

SBA-Backed Small Business Financing
SBA Microloan Business Plan
Business Plans for SBA Microloan Financing Up to $50,000
Looking to secure an SBA Microloan for your business? Mikel Consulting’s lender-ready business plans help clearly present your business model, funding request, use of funds, market opportunity, and financial outlook. Whether you are launching, expanding, purchasing equipment, or strengthening working capital, we can help you prepare a professional financing package for review by an SBA-approved intermediary lender.
Built to Support SBA Microloan Applications
Includes:
- SBA Microloan-ready business plan
- Loan request and use of funds
- Financial projections and repayment analysis
- U.S. market research and operating strategy
SBA Microloan Program Overview
What is the SBA Microloan Program?
The SBA Microloan Program provides loans of up to $50,000 to help eligible small businesses and certain not-for-profit childcare centers start and expand. SBA provides funding to specially designated nonprofit intermediary lenders, which make the loans, set the terms, and make the credit decisions for eligible borrowers.
Mikel Consulting Record of Success
Trusted by entrepreneurs, startups, and small businesses seeking financing
Microloan Financing Supported
What Are SBA Microloans?
SBA Microloans are smaller business loans of up to $50,000 made through SBA-approved intermediary lenders. They can support working capital, inventory, supplies, furniture, fixtures, machinery, and equipment for eligible small businesses.
Who Are SBA Microloans For?
Microloans are designed for eligible U.S. small businesses and certain not-for-profit childcare centers that need smaller amounts of financing to start or grow. Borrowers work directly with an SBA-approved intermediary lender in their area.
Why Does the Business Plan Matter?
A Microloan business plan helps connect the requested financing to the company’s strategy, use of funds, market demand, operating assumptions, and financial forecast. This gives the intermediary lender a clearer view of the business case and repayment outlook.
SBA Microloan Program Guidelines
Understanding the SBA Microloan Program
The SBA Microloan Program helps eligible U.S. small businesses access smaller financing amounts through SBA-approved intermediary lenders. SBA provides funding to nonprofit community-based intermediaries, which review applications, make credit decisions, set loan terms, provide the funds, and often offer borrowers management and technical assistance.
Program Overview
What SBA Microloan Financing Can Support
SBA Microloans are designed for smaller financing needs of up to $50,000 and can support eligible small businesses that need capital to start, operate, or grow. Financing can be used for working capital and qualifying business purchases such as inventory, supplies, furniture, fixtures, machinery, and equipment.
Eligible Businesses
Eligible borrowers generally include operating, for-profit small businesses located in the United States that meet SBA size requirements. Certain not-for-profit childcare centers may also qualify under the Microloan Program.
Maximum Financing
SBA Microloans are available in amounts up to $50,000. The average Microloan is approximately $13,000, although the amount available to a specific borrower depends on the intermediary lender, financing need, and credit review.
Eligible Uses of Funds
Microloan proceeds can support working capital, inventory, supplies, furniture, fixtures, machinery, and equipment. SBA Microloan proceeds cannot be used to purchase real estate or pay existing debts.
Intermediary-Lender Approval
Businesses do not receive Microloans directly from SBA. Applicants work with an SBA-approved intermediary lender in their area, which makes the credit decision and establishes the specific terms of the loan.
Business Plan Requirements
A strong Microloan business plan should clearly explain the business model, ownership, market opportunity, funding request, use of funds, operating assumptions, management capabilities, financial projections, and expected ability to repay the loan.
Rates, Terms & Lender Requirements
Interest rates are set by the intermediary lender and are generally between 8% and 13%. The maximum repayment term is seven years. Individual intermediaries may also establish their own collateral, guarantee, documentation, and underwriting requirements.
SBA-Approved Intermediaries
Where Do You Apply for an SBA Microloan?
Microloan applications are submitted through SBA-approved intermediary lenders rather than directly through SBA or a traditional national bank. These nonprofit and community-based organizations serve specific states and regions, so available lenders depend on where your business is located.
These are examples of intermediary lenders currently listed by SBA and do not represent every participating organization. Availability varies by state and service area. Mikel Consulting helps prepare the business plan, financial projections, use of funds, and funding narrative needed to support a professional Microloan application.
Find an SBA-Approved Microlender →Service Details
SBA Microloan Business Plan Delivery Details
Sample Document Preview
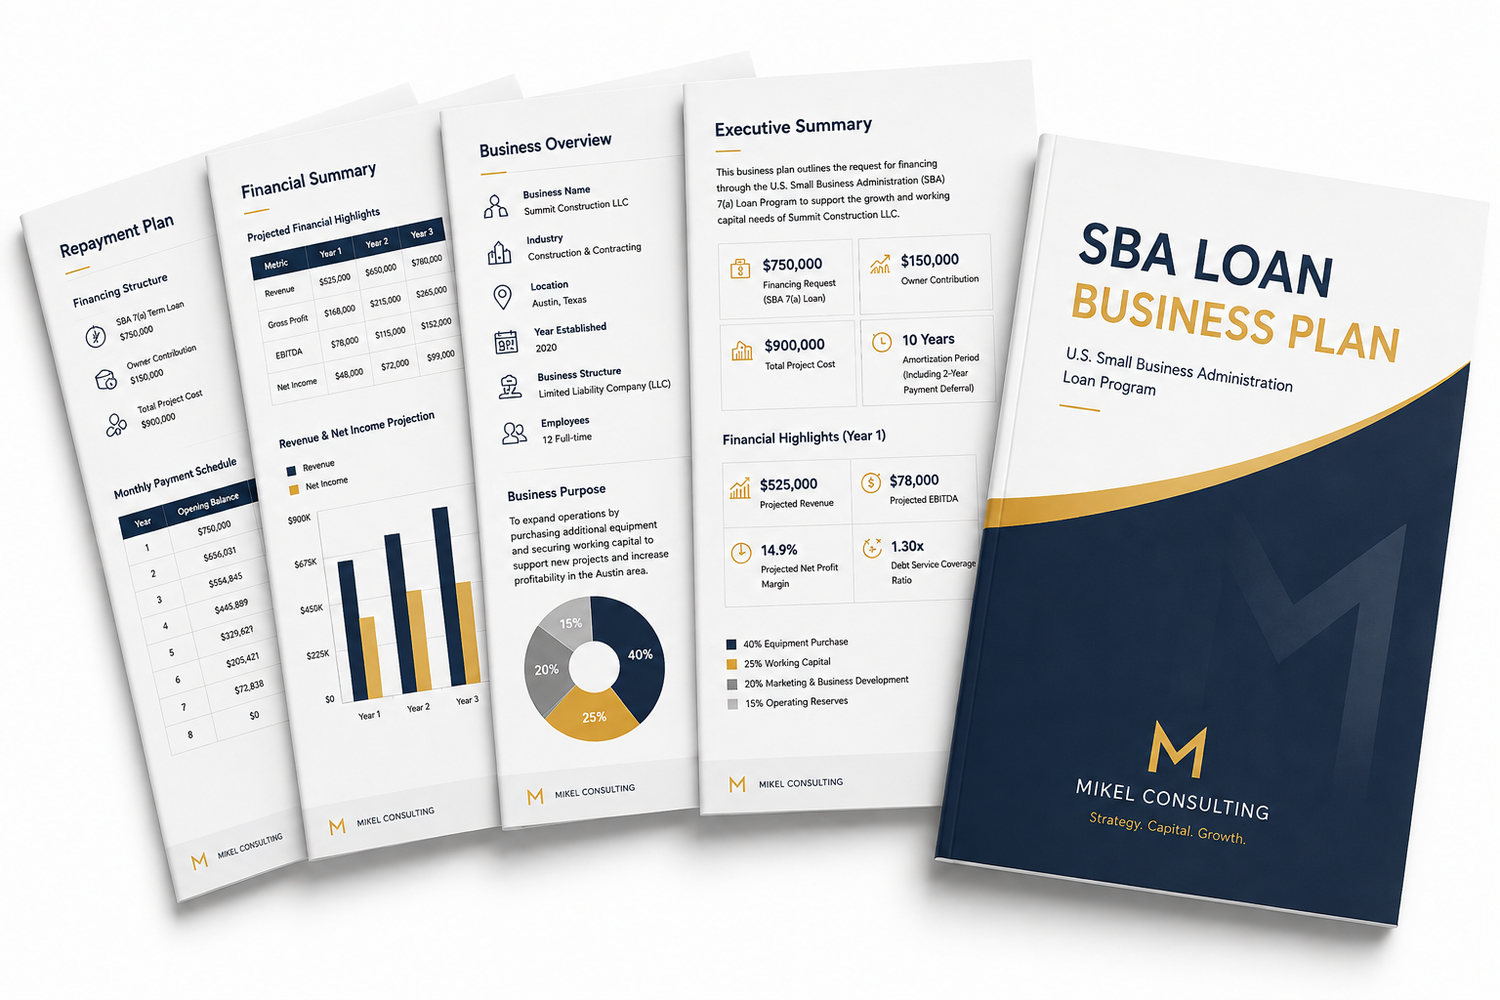
Professional, SBA Microloan-Ready Formatting
SBA Microloan business plans can include written strategy, U.S. market research, loan request details, use of funds, repayment-focused financial projections, charts, lender-ready formatting, and a clear presentation of the business case for financing.
Our Process
How Our SBA Microloan Business Plan Process Works
Intro Call or Email
We discuss your business, Microloan purpose, intermediary lender needs, and timeline.
Engagement
You receive a contract, make payment, and complete the SBA Microloan intake form.
Information Review
We review your business, use of funds, loan objectives, and financial inputs.
Plan Drafted
We prepare the plan, funding request, use of funds, market research, and forecast.
Review & Revisions
You review the draft and we refine the document for intermediary lender review.
Final Delivery
You receive polished PDF and editable files ready for SBA-approved microlenders.
Why Mikel Consulting
Why Work With Mikel Consulting for Your SBA Microloan Business Plan?
We help U.S. small businesses and startups prepare professional business plans that clearly present the Microloan request, use of funds, operating strategy, financial outlook, and repayment capacity for review by SBA-approved intermediary lenders.
Microloan-Aligned Planning
We structure the plan around the business, Microloan purpose, eligible use of funds, market opportunity, operating strategy, and financing objectives.
Built for Lender Review
We prepare the document in a clear lender-facing format so intermediary lenders can quickly understand the business, financing request, assumptions, and repayment plan.
Clear Loan Request
We explain what the business is requesting, how the funds will be used, and why the financing is important for startup, working capital, inventory, equipment, or business growth.
Financial Forecasting Support
We prepare projections that connect revenue, expenses, cash flow, startup costs, loan repayment, and the overall financial viability of the business.
Sample Business Plans
See What a Professional SBA Microloan Business Plan Can Look Like
Business Plan Sample
Restaurant Concept
See how a restaurant business plan can present the concept, market opportunity, operating model, funding request, use of funds, and repayment capacity in a clear, lender-ready format.
View Sample PDF →Expansion Plan Sample
Pilates Studio
Review a studio expansion example showing how growth plans, service offerings, local demand, startup costs, and projected performance can be structured for business loan applications.
View Sample PDF →More Examples
Browse Our Sample Library
View additional sample documents, including bank loan business plans, investor plans, pitch decks, financial models, and other funding-related examples.
Browse All Examples →Client Funding Outcomes
Real Clients. Real Financing Secured.
Explore selected client outcomes where Mikel Consulting supported loan business plans, financial projections, and lender-ready materials used in successful small business financing processes.
Explore Mikel Consulting's Success Cases →SBA Business Plan Support
Let’s Build Your SBA Business Plan
Complete the form and one of our senior consultants will review your inquiry within 24 hours. For time-sensitive SBA business plan support, call or message us directly.
🔒 Your information is strictly confidential. We do not share your details with third parties.
SBA Microloan Business Plan FAQ
Frequently Asked Questions
What is the SBA Microloan Program?
The SBA Microloan Program helps eligible small businesses access smaller amounts of financing through SBA-approved nonprofit intermediary lenders. Microloans can provide up to $50,000 for eligible business purposes such as working capital, inventory, supplies, furniture, fixtures, machinery, and equipment.
Who is eligible for an SBA Microloan?
SBA Microloans are generally available to eligible small businesses operating in the United States. Certain not-for-profit childcare centers may also qualify. Each intermediary lender establishes its own credit and underwriting requirements, so final eligibility and approval depend on the lender reviewing the application.
How much financing is available through the SBA Microloan Program?
SBA Microloans are available in amounts up to $50,000. The average Microloan is approximately $13,000. The amount available to a specific borrower depends on the business need, use of funds, repayment ability, and the underwriting requirements of the SBA-approved intermediary lender.
What can an SBA Microloan be used for?
SBA Microloan proceeds can be used for eligible business costs such as working capital, inventory, supplies, furniture, fixtures, machinery, and equipment. Microloan proceeds cannot be used to purchase real estate or repay existing business debt.
Do I apply directly to the SBA for a Microloan?
No. SBA Microloans are provided through SBA-approved intermediary lenders rather than directly by the U.S. Small Business Administration. The intermediary reviews the application, makes the credit decision, determines the loan amount, and establishes the interest rate, repayment terms, collateral requirements, and other lending conditions.
Do I need a business plan for an SBA Microloan application?
A business plan can play an important role in a Microloan application by explaining the business model, financing request, use of funds, market opportunity, operating strategy, financial outlook, and repayment capacity. Requirements vary by intermediary lender, but a professional business plan can help present the financing request clearly and support lender review.
What should be included in an SBA Microloan business plan?
An SBA Microloan business plan should typically include a company overview, ownership and management background, products or services, market analysis, target customers, competitive positioning, marketing strategy, operating plan, staffing requirements, financing request, detailed use of funds, startup or expansion costs, revenue forecast, expense forecast, cash flow projections, and repayment strategy.
What financial details do Microloan lenders look for?
Intermediary lenders may review projected revenue, gross profit, operating expenses, cash flow, startup costs, debt obligations, owner investment, repayment capacity, and the assumptions supporting the forecast. They may also want a clear use of funds schedule showing exactly how the requested Microloan will be used within the business.
Can startups apply for SBA Microloan financing?
Yes. Eligible startups can apply for SBA Microloan financing through participating intermediary lenders. Because a startup may have limited operating history, the lender may place greater emphasis on the owner's experience, business plan, market demand, startup budget, financial projections, creditworthiness, and expected ability to repay the loan.
What are SBA Microloan interest rates and repayment terms?
Interest rates are set by the intermediary lender and are generally between 8% and 13%. The maximum repayment term for an SBA Microloan is seven years. Actual rates and terms vary depending on the intermediary lender, loan size, business circumstances, collateral, and credit review.
Can an SBA Microloan business plan also be used for other business loans?
Yes. An SBA Microloan business plan can often be adapted for other SBA programs, conventional bank loans, credit union financing, CDFI financing, equipment loans, private lenders, or investor discussions. The core business strategy may remain similar, while the funding request, use of funds, repayment analysis, and lender-specific details are adjusted for the financing program.
How can Mikel Consulting help with an SBA Microloan business plan?
Mikel Consulting prepares lender-ready business plans designed to support SBA Microloan applications. We help present your business model, financing request, use of funds, U.S. market opportunity, operating strategy, management background, and financial projections in a clear and professional format for review by SBA-approved intermediary lenders.
How quickly can Mikel Consulting prepare an SBA Microloan business plan?
Most SBA Microloan business plans are completed within 7-10 business days once we have the required information. The timeline can vary depending on the complexity of the business, number of revenue streams, level of market research required, financial information available, and intermediary lender requirements.
Do you guarantee SBA Microloan approval?
No. We prepare professional business plans designed to support lender review, but we cannot guarantee loan approval. SBA Microloans are approved by participating intermediary lenders, and decisions depend on factors such as eligibility, credit history, cash flow, collateral requirements, repayment capacity, lender policies, and the overall risk profile of the application.
How much does an SBA Microloan business plan cost?
Our SBA Microloan business plans start at $1,000 USD. This typically includes a professionally written business plan, U.S. market research, financial projections, use of funds breakdown, and delivery in PDF and editable formats. Most SBA Microloan business plans are approximately 30-40 pages and are completed within 7-10 business days.